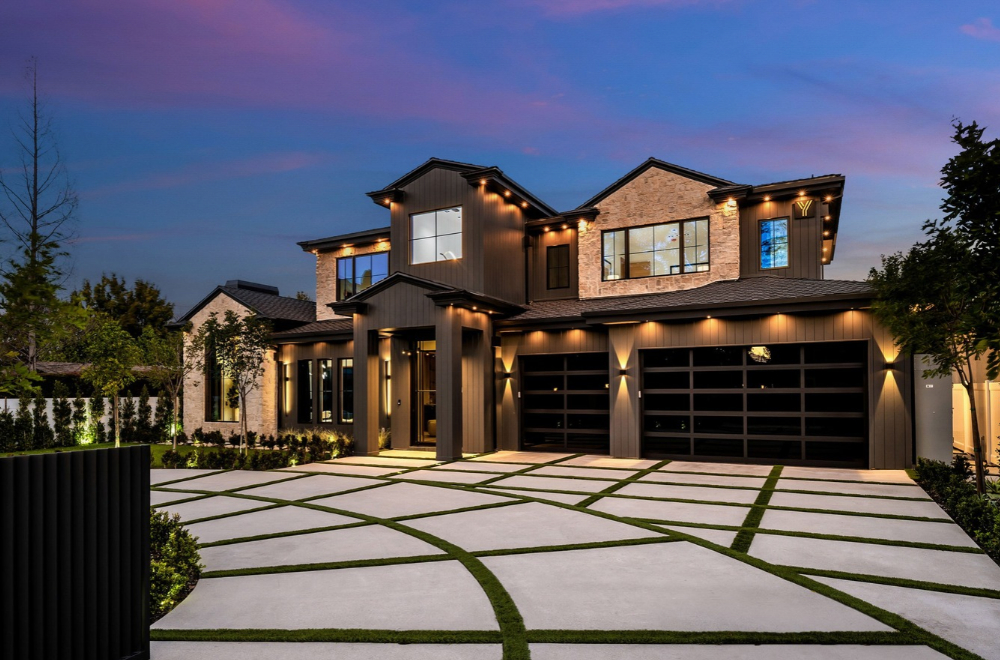
Orinda’s wooded hills, narrow roads, and large custom homes create a property-risk profile that cannot be judged from a ZIP code alone. The city has said that a high percentage of local homes sit in Very High Fire Hazard Severity Zones, while residents have faced nonrenewals and difficulty finding replacement coverage. Old Harbor Insurance helps Orinda homeowners compare admitted, surplus-lines, and California FAIR Plan options with the property itself in view.
A useful home insurance review begins with the rebuild, not the sale price. Roof shape, slope access, vegetation, private roads, retaining walls, interior finishes, and recent additions can all affect eligibility and the amount of coverage needed. An independent agent can gather those details once, approach suitable markets, and explain where a quote is narrower than the homeowner expects.
Why Home Insurance in Orinda Requires a Property-Level Review
Orinda’s fire exposure varies sharply from one parcel to the next. A home near open space may have different access, brush, ember, and evacuation conditions from a home closer to downtown, even when both share the 94563 ZIP code. The City of Orinda’s letter on the insurance nonrenewal crisis notes both the city’s concentration of homes in very high fire-hazard areas and the local scale of resident concern.
Underwriting can therefore turn on details that a basic online form does not capture well. Carriers may ask about roof age and material, defensible space, brush clearance, prior losses, electrical and plumbing updates, distance to a hydrant or fire station, road width, and whether firefighters can reach the structure safely.
Hillside Access Changes Both Fire and Rebuilding Risk
Steep driveways and winding private roads can affect emergency access during a wildfire. They can also increase the cost of debris removal, material delivery, equipment staging, and labor after a covered loss. A dwelling limit based on a flat-lot estimate may leave a hillside owner exposed even when the home’s square footage looks ordinary on paper.
Orinda homeowners should tell their agent about gates, bridges, long driveways, difficult turnarounds, detached structures below the main house, and any access shared with neighbours. Those features belong in the underwriting file and in the replacement-cost discussion.
Build Coverage Around the Cost to Reconstruct the Home
Market value includes land, location, school access, and buyer demand. Dwelling coverage is meant to pay for covered damage to the structure, so it should be tied to the likely cost of reconstruction. For a custom Lamorinda home, that estimate may need to account for architectural plans, premium finishes, specialty trades, code upgrades, and a longer construction timeline.
Extended replacement cost can add a percentage above the listed dwelling limit when a covered catastrophe drives costs higher, but the percentage and conditions differ by policy. Guaranteed replacement cost is less common and still depends on the insured meeting policy requirements. Neither feature excuses an outdated starting limit.
Ordinance and Law Coverage Deserves Separate Attention
Older homes may have to meet current building, energy, electrical, seismic, or wildfire-resistance standards during a major repair. Ordinance and law coverage can help with eligible costs to demolish undamaged portions, rebuild to current code, or address the gap between the old construction and legally required work.
The limit should reflect the home’s age and complexity rather than a default percentage selected years ago. A remodel, new roof, electrical upgrade, room addition, or permitted accessory dwelling unit is a reason to revisit both the dwelling estimate and code-upgrade protection.
Treat Wildfire Mitigation as Evidence, Not a Checkbox
Orinda has unusually specific local resources for reducing wildfire exposure. The city lists fuel pickups, matching incentives, home assessments, defensible-space material, and evacuation information through its emergency preparedness program. The point of this work is life safety first, but good documentation can also make an insurance submission clearer.
Keep dated photographs, invoices, inspection reports, and details of completed work. Show the roof covering, vents, eaves, deck area, fencing near the structure, tree spacing, and the first five feet around the house. Ask the agent which documents a carrier will accept and whether the work qualifies for a rating credit.
Local Requirements Can Affect the Underwriting Conversation
The Moraga-Orinda Fire Protection District’s rules are not generic advice. For example, its wildfire mitigation notice requires juniper and bamboo within ten feet of paved public or private roads to be removed because those plants can impede evacuation and first-responder access when they burn.
Compliance does not guarantee that a carrier will offer coverage. It does, however, prevent a local hazard issue from becoming an avoidable weakness in the file. Homeowners should also request a home assessment when they are unsure what work has the highest priority.
Choose the Right Market Before Comparing Premiums
An admitted carrier is regulated by the California Department of Insurance and participates in the state guaranty system. A surplus-lines carrier can cover harder-to-place or unusual risks with more flexible forms and pricing, but it does not carry the same guaranty-fund protection. The California FAIR Plan is a last-resort option for basic property coverage when the traditional market is unavailable.
The cheapest quote may exclude water damage, reduce loss-of-use protection, limit roof settlement, or offer a much higher deductible. Compare the form, exclusions, sublimits, replacement-cost terms, and claims conditions before comparing the final premium. Old Harbor’s explanation of how property policies respond to covered claims is a useful starting point for reading those differences.
A FAIR Plan Policy Usually Needs Companion Coverage
The FAIR Plan is designed primarily for fire and named-peril protection. A Difference in Conditions policy may be needed to add liability, theft, water damage, and other protections associated with a broader homeowners form. The two policies must be reviewed together so deductibles, exclusions, and effective dates do not create gaps.
A private-market policy is generally preferable when it provides sound coverage at a sustainable price. Where it does not, an agent should explain why the FAIR Plan combination is being recommended and what is still excluded.
Protect More Than the Main Structure
Orinda properties often include detached garages, studios, guest spaces, pools, solar equipment, retaining walls, extensive landscaping, and long runs of fencing. Some of these items fall under other-structures coverage, some have special limits, and some may not be covered for the same causes of loss as the dwelling.
Personal property also deserves more than a rough percentage. Jewelry, art, wine, musical instruments, collectibles, and business equipment may need scheduled coverage or a specialty policy. A room-by-room inventory with photographs and receipts makes both the coverage review and a future claim more precise.
Loss of Use Must Match a Realistic Rebuild Timeline
A major hillside reconstruction can take longer than a standard repair. Debris removal, engineering, design review, permits, contractor availability, and code compliance may delay occupancy. Check whether loss-of-use coverage is limited by dollars, months, or both, and whether the amount can support comparable temporary housing in Lamorinda.
Owners who rent part of the property should also distinguish additional living expense from lost rental income. They solve different problems and may require different policy language.
How Old Harbor Insurance Helps Orinda Homeowners
Old Harbor starts by identifying the property details that can change eligibility or coverage: fire-hazard designation, access, construction type, roof, mitigation work, rebuild estimate, prior claims, occupancy, and valuable features. That information lets the agency approach appropriate carriers without presenting the home as a generic California risk.
The comparison then moves line by line. Homeowners can see whether an option is admitted or non-admitted, how the deductible works, what replacement-cost protection applies, whether water and liability are included, and where a companion policy is needed. The aim is a defensible coverage decision, not a stack of unexplained prices.
Review Your Orinda Home Coverage Before the Next Renewal
Begin the review while the current policy is still active. Gather the declaration pages, renewal offer or nonrenewal notice, recent inspection documents, roof and system updates, mitigation records, and a list of additions or high-value property. Contact Old Harbor Insurance to discuss the home’s risk profile, or request a home insurance quote when the information is ready.
Frequently Asked Questions
Does a Firewise neighbourhood guarantee a lower home insurance premium?
A Firewise designation does not guarantee a premium reduction or an offer of coverage. Some carriers recognize community mitigation, but each company applies its own eligibility rules, documentation standards, and rating credits.
Will removing trees automatically make an Orinda home insurable?
Tree removal alone does not automatically make a home insurable. Underwriters may consider vegetation spacing, overhanging limbs, roof and vent construction, slope, road access, nearby fuels, and the condition of surrounding parcels together.
Can I insure a vacant Orinda home during a major renovation?
A standard homeowners policy may restrict or exclude losses after a home becomes vacant or enters major construction. A builder’s risk, course-of-construction, or vacant-home form may be needed before work begins.
Are retaining walls covered by a homeowners policy?
Retaining-wall coverage depends on the policy form, cause of loss, location, and applicable other-structures limit. Earth movement, settling, hydrostatic pressure, and faulty construction are commonly restricted or excluded.
Does home insurance cover landslides on Orinda hillsides?
Standard home insurance generally excludes earth movement, including landslides and mudslides. Specialized difference-in-conditions or earth-movement options may exist, but terms and capacity are limited.
How does a percentage wildfire deductible work?
A percentage deductible is calculated from the insured dwelling limit, not from the amount of the claim. On a home insured for $2 million, a 2% deductible would equal $40,000 before covered payment calculations.
Should a home be reinsured after an addition or major remodel?
A home should be reviewed as soon as an addition or major remodel changes its size, finishes, systems, or replacement cost. Waiting until renewal can leave the declared dwelling amount and property description out of date during construction or after completion.