According to Redfin, Brentwood’s median home sale price reached $2.4 million in August 2026 (~$985 per square foot), down 9.58% year-over-year. Old Harbor Insurance provides homeowners insurance in Brentwood, CA, a Westside community where estates in Mandeville Canyon and Sullivan Canyon border brush-covered hillsides that have experienced three major wildfires since 2017.
Many existing policies were purchased prior to recent home renovations, guest house additions, or the Palisades Fire’s impact on Westside underwriting standards. If your dwelling limit hasn’t been updated recently, your coverage may fall short, a gap that often goes unnoticed until a claim is filed.
What Home Insurance Covers for a Brentwood Property
Standard California homeowners policies are built around five core areas: dwelling, other structures, personal property, liability, and loss of use. However, high-value properties in Brentwood require broader protection across each component.
Dwelling limits must reflect specialized hillside construction costs, detached structure coverage should account for guest houses or equestrian facilities, and liability policies must extend to features like pools, tennis courts, and household staff.
| Coverage Type | What It Addresses |
| Dwelling / replacement cost | Rebuilding a custom hillside home at current labor and material costs |
| Other structures | Guest houses, pool houses, equestrian barns, gated entries |
| Personal property | Furnishings and belongings, with scheduling for higher-value items |
| Liability | Injuries to guests, contractors, or staff, including pool and equestrian exposure |
| Loss of use | Temporary housing while a covered loss is repaired |
| Ordinance or law | Added cost of meeting current fire code requirements during a rebuild |
Guaranteed Replacement Cost for Canyon Estates
Building or rebuilding on a Brentwood hillside lot costs more per square foot than flat-lot construction, once an engineered foundation, retaining walls, and getting equipment up a narrow canyon road all get factored in.
A guaranteed or extended replacement cost endorsement pays to rebuild at current labor and material costs instead of stopping at a dwelling limit that was set years before any of that got priced in.
Defensible Space & Fire Zone Requirements
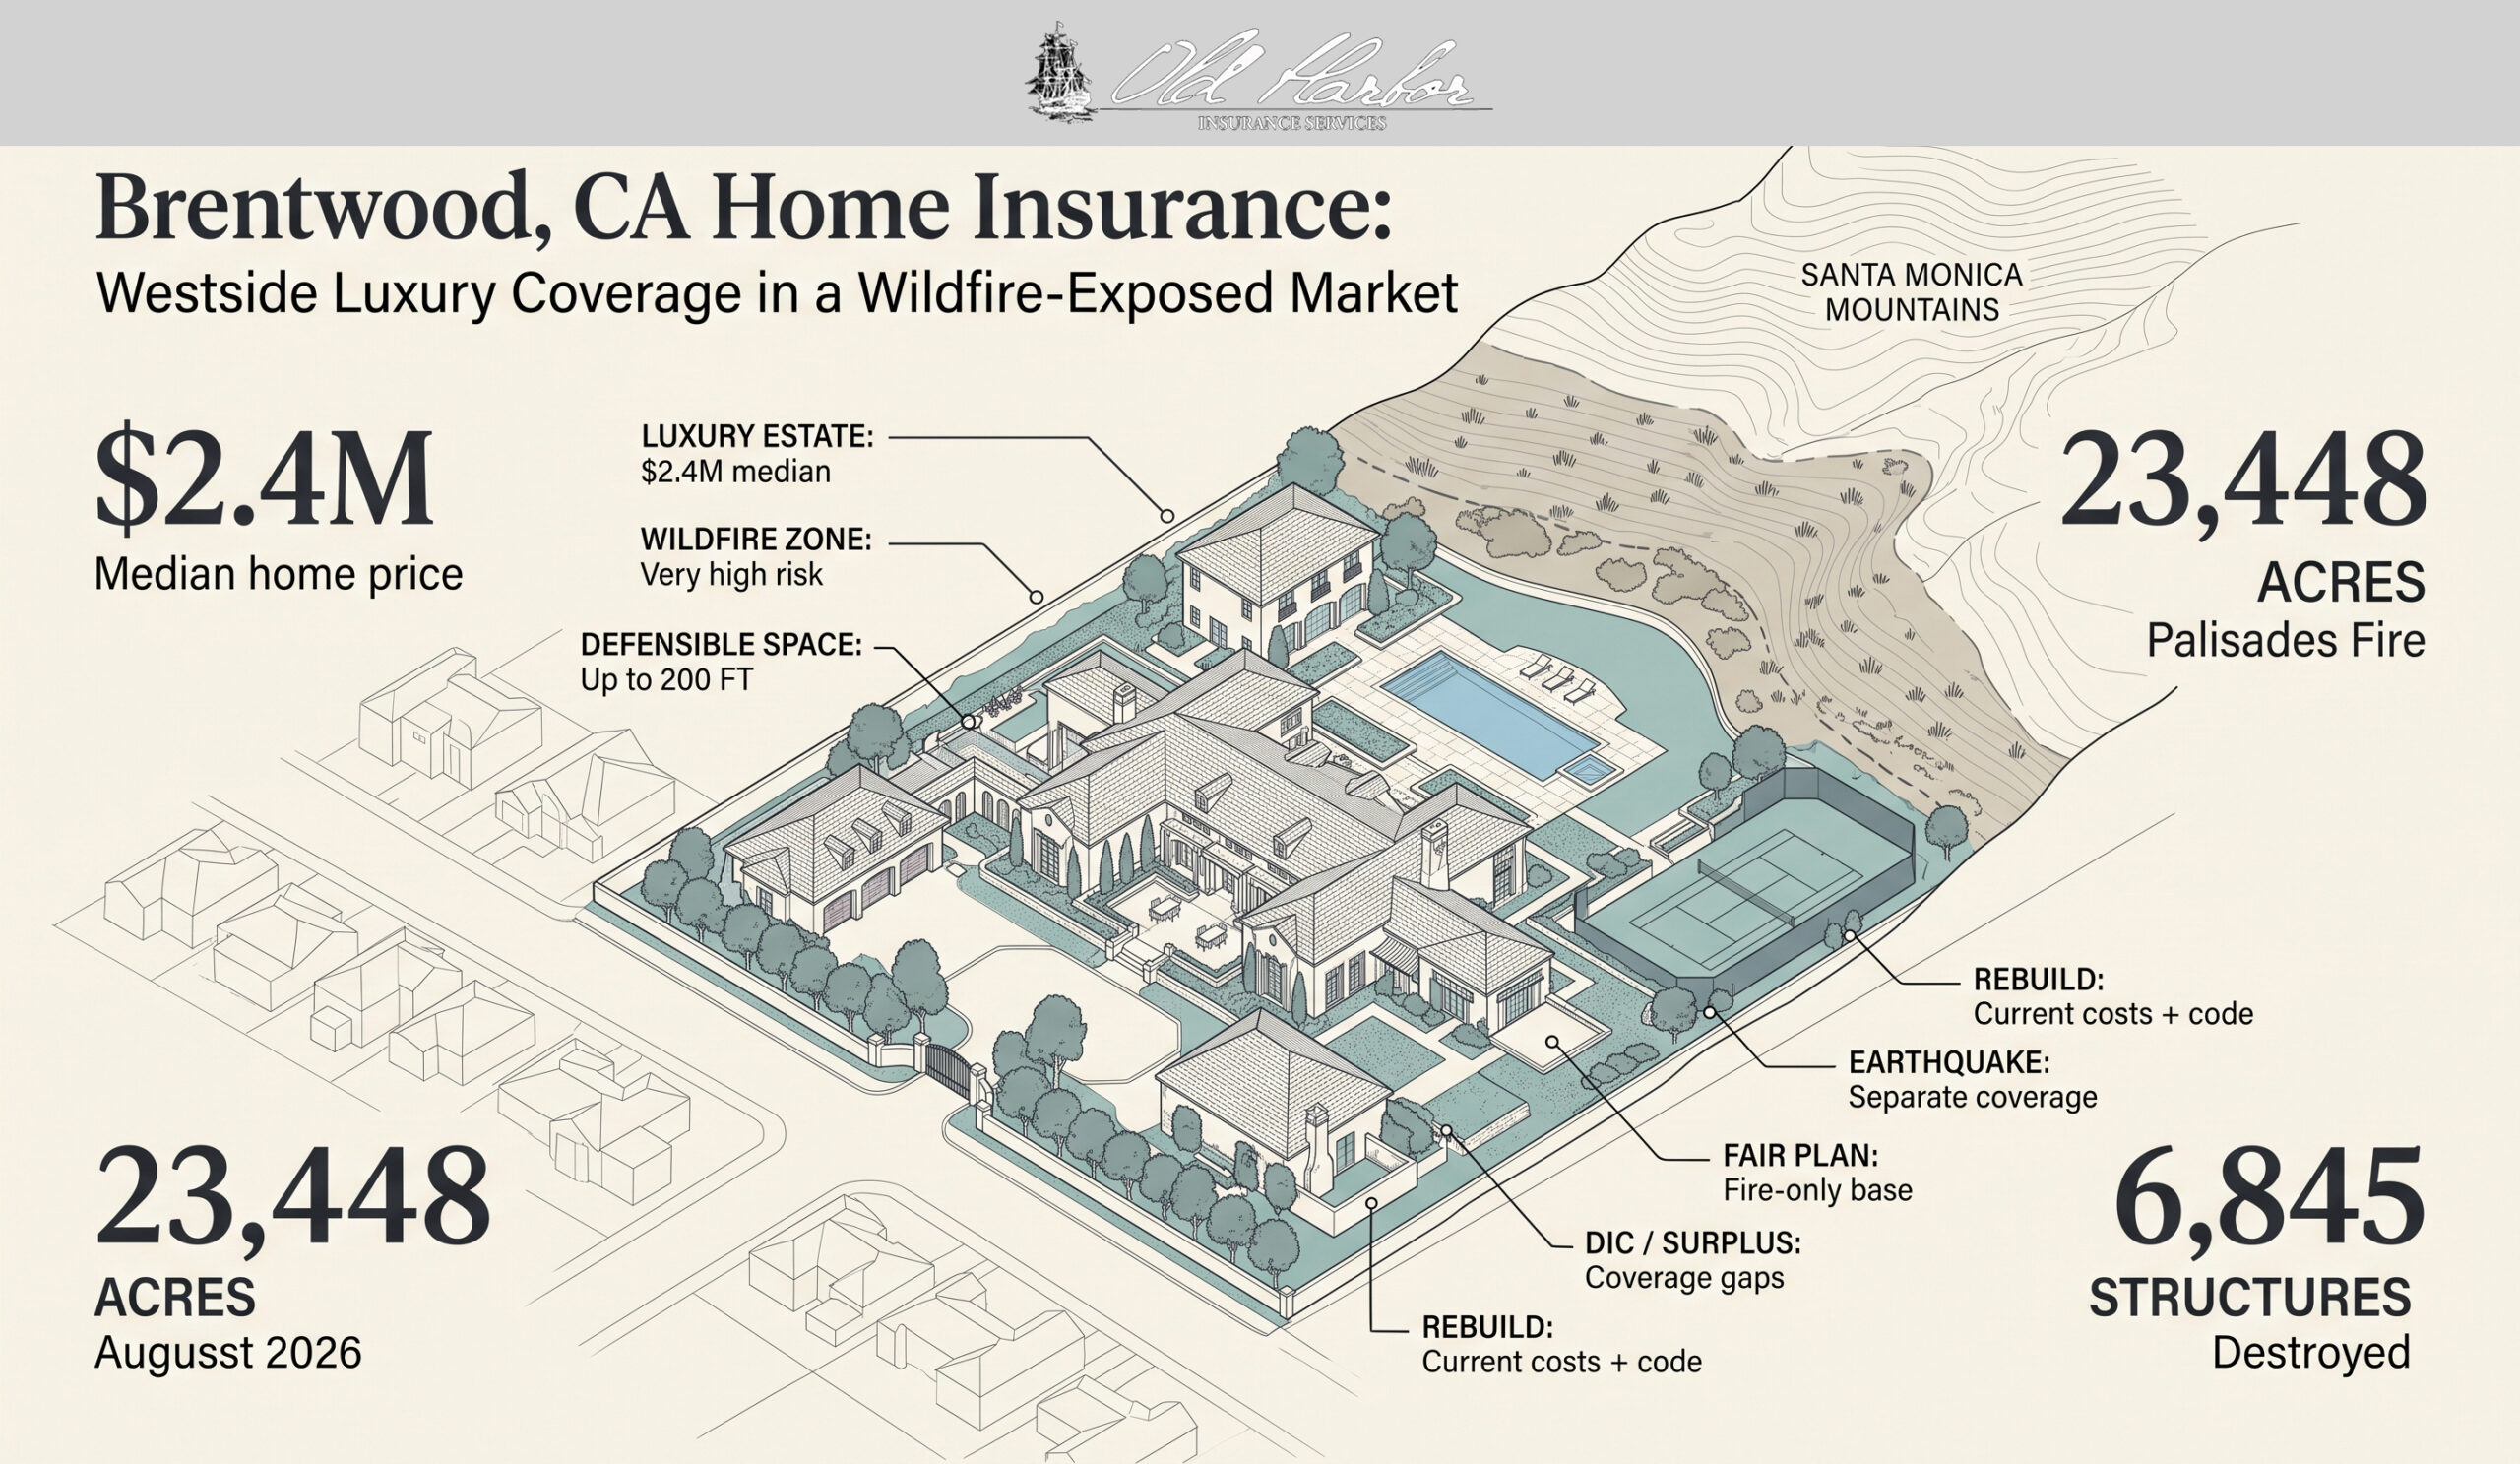
The Los Angeles Fire Department classifies the hillside terrain stretching from Mulholland Drive down to Sunset Boulevard, encompassing most of Brentwood’s canyon neighborhoods, as part of the city’s Very High Fire Hazard Severity Zone.
According to LAFD’s fire zone history, properties within this area must maintain brush clearance up to 200 feet from structures where terrain allows. Additionally, an increasing number of carriers now require proof of brush mitigation, hardened vents, and a Class A roof prior to issuing or renewing a policy within the zone.
Wildfire Risks in the Brentwood Market
A Pattern That Goes Back to 1961
On November 6, 1961, the Bel Air Fire swept over the ridge from Sherman Oaks, driven by 60 mph Santa Ana winds, and destroyed 484 homes. This event prompted the city of Los Angeles to establish its Mountain Fire District, the predecessor to today’s Very High Fire Hazard Severity Zone, according to LAFD’s fire zone history.
Decades later, the Getty Fire ignited at 1800 North Sepulveda Boulevard in Brentwood on October 28, 2019. It burned 745 acres and destroyed 10 homes before being fully contained on November 5, per the Los Angeles Fire Department.
The Palisades Fire Impact
According to CAL FIRE’s incident record, the Palisades Fire burned 23,448 acres and destroyed 6,845 structures before achieving full containment on January 31, 2025. On January 11, the fire shifted eastward toward the 405 Freeway and reached Mandeville Canyon, destroying at least one Brentwood home and prompting fresh evacuation orders from San Vicente Boulevard north to the Encino Reservoir, as reported by FOX 11 Los Angeles.
Santa Monica Fault Risk
The Santa Monica Fault cuts through the heart of the Westside, with mapped sections running beneath Century City, Westwood, Brentwood, Santa Monica, and Pacific Palisades, according to California Geological Survey mapping reported by the Santa Monica Mirror.
However, earthquake damage is completely excluded from standard California homeowners policies, regardless of fault proximity. Securing protection requires a separate policy through either the California Earthquake Authority or a private insurance carrier.
California FAIR Plan Coverage & Limitations
In 2026, the California Department of Insurance introduced legislation to overhaul the FAIR Plan following an internal review revealing that the insurer of last resort had only partially implemented 17 of 32 mandated reforms regarding governance, finances, and consumer protections.
The review occurred after the department sued the FAIR Plan for denying smoke damage claims stemming from wildfires that resulted in $22.4 billion in payouts since January 2025. Consequently, Brentwood properties insured under the FAIR Plan due to high-risk zoning may face coverage limitations alongside administrative challenges.
Most policyholders utilizing the FAIR Plan supplement it with a Difference in Conditions (DIC) policy, as the FAIR Plan exclusively covers fire damage while omitting coverage for theft, water damage, and liability.
Furthermore, because many high-value Brentwood homes exceed the FAIR Plan’s residential dwelling limit, owners must secure coverage through the FAIR Plan’s dedicated high-value program or a surplus lines carrier via a licensed broker who can confirm that the admitted market has been fully evaluated.
Brentwood Home Insurance Costs
Although premium rates reflect total replacement costs rather than market values, Brentwood’s average sale price of approximately $985 per square foot provides a useful benchmark for estimating baseline dwelling coverage.
Location remains the primary pricing factor, with rates heavily influenced by a property’s designation within the Very High Fire Hazard Severity Zone and its proximity to recent wildfire perimeters.
After that, it comes down to the house itself. A Class A roof, ember-resistant vents, and documented brush clearance can mean a real price difference between two homes on the same street, built the same year.
How Old Harbor Insurance Helps
Old Harbor works with more than 80 A-rated carriers across the admitted market, the FAIR Plan’s high-value program, and surplus lines, so a Brentwood property isn’t limited to whatever one company still wants to write at renewal. For a hillside estate that needs guaranteed replacement cost, a DIC policy, and umbrella liability together, that’s one coordinated plan instead of three quotes that don’t match up.
How a claim actually moves from filing to payout is good to know before the next fire season, not during it. Which carriers are still writing new policies in Brentwood’s fire zone changes throughout the year, so an option that wasn’t there last renewal might be back now.
Protect Your Brentwood Property the Right Way
A policy bought before the Palisades Fire, before a renovation, or before a guest house or pool went in probably doesn’t match the home as it stands today.
Contact Old Harbor Insurance to go over how a specific Brentwood address is covered right now, or request a quote to compare standard, FAIR Plan, and surplus-lines options side by side.
Frequently Asked Questions
Does homeowners insurance cover food spoilage or losses from a preemptive power shutoff during a red flag warning?
Most standard homeowners policies exclude food spoilage and other losses caused by a power outage alone, including a Public Safety Power Shutoff called during high-wind fire weather. Some carriers offer a utility interruption endorsement covering spoilage once the outage passes a set number of hours.
Can an insurer non-renew a Brentwood policy immediately after a fire like the Palisades Fire burns nearby?
California law bars an admitted insurer from non-renewing a policy for one year after the governor declares a state of emergency for a wildfire, if the home sits within or adjacent to the fire perimeter. That moratorium doesn’t apply to homes outside the declared area, so a Brentwood property just beyond the boundary line can still get a non-renewal notice.
Does a standard homeowners policy cover smoke and ash damage to a home that wildfire never directly touched?
Smoke and ash damage from a nearby wildfire is typically a covered peril under a standard homeowners policy, even when flames never reached the structure itself. An insurer may still dispute how much cleanup is actually needed, which is why documenting HVAC contamination and surface damage right after an evacuation lift matters.
Do Sullivan Canyon’s private equestrian properties need liability coverage beyond a standard homeowners policy?
A horse boarded or ridden on a private Sullivan Canyon property typically falls outside a standard policy’s animal liability limits once lessons, boarding, or organized events are involved. A separate equine liability policy or farm endorsement covers that commercial-adjacent activity instead.
Does an umbrella policy extend to a guest house rented out short-term near UCLA or the Brentwood Country Mart?
An umbrella policy generally excludes liability from a short-term rental once the property is used commercially, even for a guest house separate from the main residence. A short-term rental endorsement or a dedicated hosting policy is the right fit for a Brentwood guest house booked through a rental platform.
What deductible should a Brentwood homeowner expect on a California Earthquake Authority policy?
A California Earthquake Authority policy typically carries a deductible between 5 and 25 percent of the dwelling’s insured value, and most homeowners land somewhere near the middle of that range. That’s a lot more than a standard homeowners deductible, and it changes the math on whether earthquake coverage makes sense for a given budget.
Does ordinance or law coverage pay for hardened vents or a Class A roof required after a Very High Fire Hazard Severity Zone reinspection?
Ordinance or law coverage applies only when a covered loss triggers a rebuild that must meet current code, not to voluntary upgrades made ahead of an inspection. A homeowner who hardens a roof or replaces vents before any damage occurs usually pays for that work directly, though it can improve how a carrier prices the policy going forward.