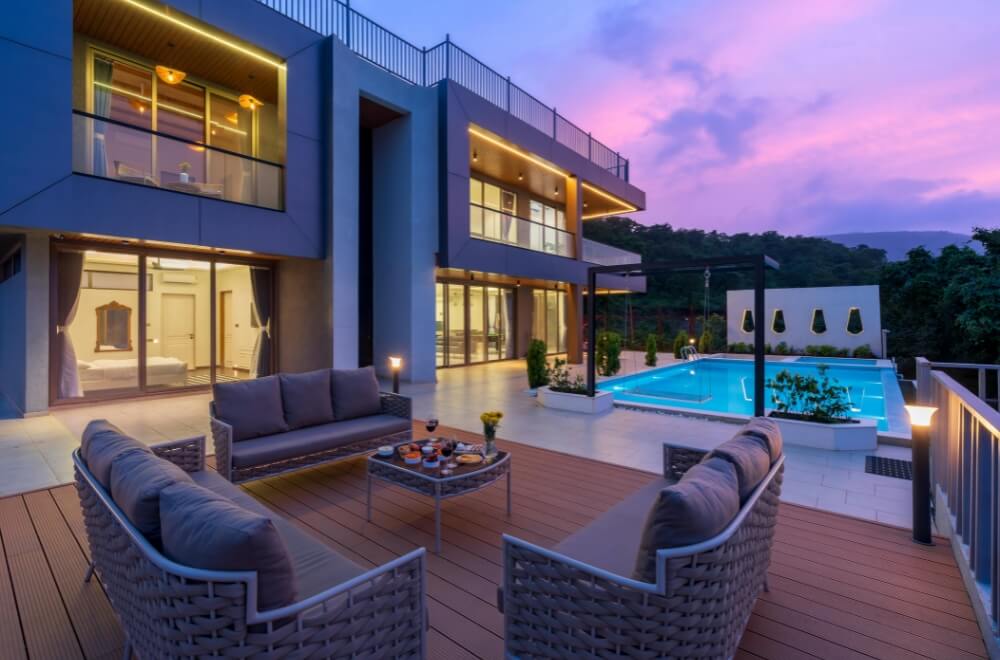
Holmby Hills, part of the “Platinum Triangle” alongside Bel-Air and Beverly Hills, was platted a century ago into some of the largest residential lots in Los Angeles, and that scale still shows in the price: homes here sold for a median $11.567 million as of November 2025, according to Redfin.
Old Harbor Insurance writes coverage for homeowners whose properties, and the guest houses, pools, and staff quarters around them, cost more to rebuild than a standard homeowners policy was ever priced for.
California’s FAIR Plan caps a standard residential dwelling policy well below what a property like this is worth. A policy written years ago, before a screening room or wine cellar was added, may not reflect what the house would cost to rebuild today. It’s worth checking the dwelling limit, scheduled property, and liability sections against the home as it stands now, instead of discovering a mismatch once a claim is already underway.
What High-Value Estate Insurance Covers in Holmby Hills
A policy on an estate like this covers the same five things any homeowner’s policy does: dwelling, other structures, personal property, liability, and loss of use. What changes is the scale. Rebuild costs can run to eight figures, an art collection usually needs its own appraisal, and a house with live-in staff or paid filming carries liability exposure most standard policies weren’t written to handle.
| Coverage Type | What It Addresses |
| Dwelling / guaranteed replacement cost | Rebuilding a custom estate at current labor and material costs, often above the FAIR Plan’s residential cap |
| Other structures | Guest houses, pool houses, screening rooms, subterranean additions |
| Scheduled personal property | Fine art, jewelry, wine collections, and cars above standard sublimits |
| Liability and umbrella | Injuries to guests, household staff, or contractors, including exposure from filming or events |
| Loss of use | Temporary housing while a multi-year rebuild is underway |
Guaranteed Replacement Cost Above Standard Limits
An estate with imported stonework, a subterranean addition, or a decades-old mansion that’s been through several renovations usually costs more per square foot to rebuild than a generic online estimator assumes. A guaranteed or extended replacement cost endorsement pays to rebuild at current labor and material prices instead of stopping at whatever dwelling limit got set years earlier.
Scheduled Coverage for High-Value Collections
Standard homeowners policies cap jewelry, watches, and fine art at a few thousand dollars combined, a sublimit that rarely covers a single painting in a serious collection. A scheduled personal property endorsement, usually built from a professional appraisal, insures each item at its own value instead of lumping it into that cap. Wine cellars and car collections typically need their own schedule too.
Liability Coverage for Staff, Guests, and Filming
General liability covers a guest, contractor, or household employee who’s hurt on the property, an exposure that only grows with a pool, a screening room, or full-time staff on-site. Plenty of Holmby Hills estates also get rented out for photo shoots and filming, which needs its own commercial general liability coverage on top of whatever the production carries.
How a claim like that gets handled is worth understanding before signing a location agreement, not after. An umbrella policy stacked above the home and auto limits is a cheap way to add real protection, often just $150 to $200 a year for the first layer.
Distinct Coverage Challenges in Holmby Hills
Concentrated FAIR Plan Exposure in Luxury Markets
Nine California zip codes, most of which are affluent communities with a high proportion of secondary residences, account for roughly 7% of the FAIR Plan’s total liability exposure. This represents approximately $44 billion as of September 2025, reflecting a 135% surge since 2022, according to Insurance Journal’s reporting on luxury homes and the FAIR Plan.
Such heavy geographic concentration helps explain why applications for high-value Los Angeles properties often face stricter underwriting scrutiny than their individual risk profiles alone might suggest.
Proximity to the Santa Monica Fault Zone
The Santa Monica Fault Zone, capable of producing a magnitude 7.0 earthquake, runs beneath the Beverly Hills shopping district bordering Holmby Hills, according to a 2018 California Geological Survey evaluation reported by CBS News.
Standard homeowners insurance excludes earthquake damage everywhere in California, so coverage for a property this close to a major fault has to come from the California Earthquake Authority or a private carrier.
FAIR Plan Alternatives for High-Value Estates
Exceeding Standard Dwelling Limits
The California FAIR Plan’s residential dwelling limit is no longer fixed where it once was. Insurance Commissioner Ricardo Lara doubled the limit to $3 million in 2019 following two decades without an update, while a separate California FAIR Plan Association announcement raised the commercial and high-value program cap to $20 million per location.
However, with homes in Holmby Hills fetching near the median sale price, rebuild costs regularly exceed the residential threshold. Consequently, property owners must apply under the commercial and high-value program or look beyond the FAIR Plan entirely.
Surplus Lines and Difference-in-Conditions (DIC) Coverage
A non-admitted surplus lines carrier can issue a single, broader multi-peril policy with coverage limits tailored to an eight-figure rebuild, something the FAIR Plan’s fire-only coverage is not designed to handle alone.
When a FAIR Plan policy is appropriate for a portion of the risk, pairing it with a Difference in Conditions (DIC) policy fills critical coverage gaps, including liability, theft, and water damage. Securing a surplus lines policy requires a licensed broker to document that the admitted market was evaluated first.
Insurance Costs for Holmby Hills Estates
Premiums depend on the dwelling’s rebuild cost, the value of separately scheduled items, whether the property is used for filming, and how many carriers are actively seeking high-value coverage in that price range.
A property receiving standard coverage during one renewal cycle can be shifted to surplus lines the next, not due to changes at the house, but because a carrier’s appetite for luxury risk has shifted.
Renovation history moves the number too. A subterranean addition or an expanded wine cellar raises the rebuild cost, and a policy still priced off the original construction won’t reflect that until someone orders a new appraisal.
How Old Harbor Insurance Helps
Old Harbor works with more than 80 A-rated carriers, covering the admitted market, the FAIR Plan’s high-value program, and surplus lines in one search instead of three. For a property that needs guaranteed replacement cost, scheduled valuables, and umbrella liability priced together, that range is the difference between one coordinated policy and three that don’t line up.
Which carriers are writing new high-value business in Los Angeles changes fairly often. A property that only qualified for the FAIR Plan’s program a year ago can sometimes get a standard quote now, though that’s usually only obvious at renewal.
Protect a Holmby Hills Estate the Right Way
A policy bought before a renovation, a new collection, or a change in how the property gets used is worth a second look. Contact Old Harbor Insurance to go over how a Holmby Hills property is covered right now, or request a quote to compare standard, high-value, and surplus-lines options.
Frequently Asked Questions
Does the FAIR Plan’s standard residential dwelling limit cover a typical Holmby Hills home?
The FAIR Plan’s standard residential dwelling limit falls well below what most Holmby Hills properties would cost to rebuild. A home priced near the neighborhood’s median sale value typically needs the FAIR Plan’s separate commercial or high-value program, or coverage outside the FAIR Plan entirely, to insure the full rebuild cost.
Does a standard homeowners policy cover a home rented out for a photo shoot or film production?
A standard homeowners policy generally excludes liability from commercial activity, including a paid film or photo shoot. Production companies typically carry their own coverage for a shoot, but a homeowner hosting recurring location work should still get a separate commercial general liability policy.
Are below-grade additions like a subterranean wine cellar or home theater automatically included in a dwelling’s coverage limit?
A below-grade addition isn’t automatically reflected in an older policy’s dwelling limit unless the insurer was notified when the work was finished. Underground construction in Los Angeles typically costs more per square foot than above-grade space, so an unreported addition can leave a real gap between the policy limit and the actual rebuild cost.
Does homeowners insurance in California include kidnap and ransom or personal security coverage for high-profile owners?
Kidnap and ransom coverage isn’t included in a standard homeowners policy and gets written as its own specialty policy, often through a carrier that also handles high-net-worth personal lines. Some umbrella policies offer a limited crisis-management rider, but a dedicated policy covers more for an owner whose public profile makes that a real consideration.
Do California homeowners need earthquake coverage even if their home has never been near a major quake?
Standard homeowners insurance excludes earthquake damage everywhere in California, regardless of a property’s claims history or distance from a known fault. Coverage requires a separate policy through the California Earthquake Authority or a private carrier, and a fault going quiet for a few centuries doesn’t say much about when it might move again.
How long does loss-of-use coverage typically last during the rebuild of a large custom estate?
Standard loss-of-use coverage often caps temporary housing reimbursement at a set dollar amount or 12 to 24 months, a window sized for an ordinary rebuild rather than a custom estate that takes longer to permit and construct. An extended endorsement, priced to what temporary housing rents for locally, is usually the fix.
Does an umbrella policy cover a household employee driving the owner’s vehicle?
An umbrella policy generally extends liability coverage to a household employee driving an owner’s vehicle with permission, subject to the terms of the underlying auto policy it sits above. Confirming the employee is listed as an authorized driver on that auto policy still matters, since the umbrella policy follows the underlying coverage rather than replacing it.